
Small payments, big payoff changes
How extra payments reduce debt faster
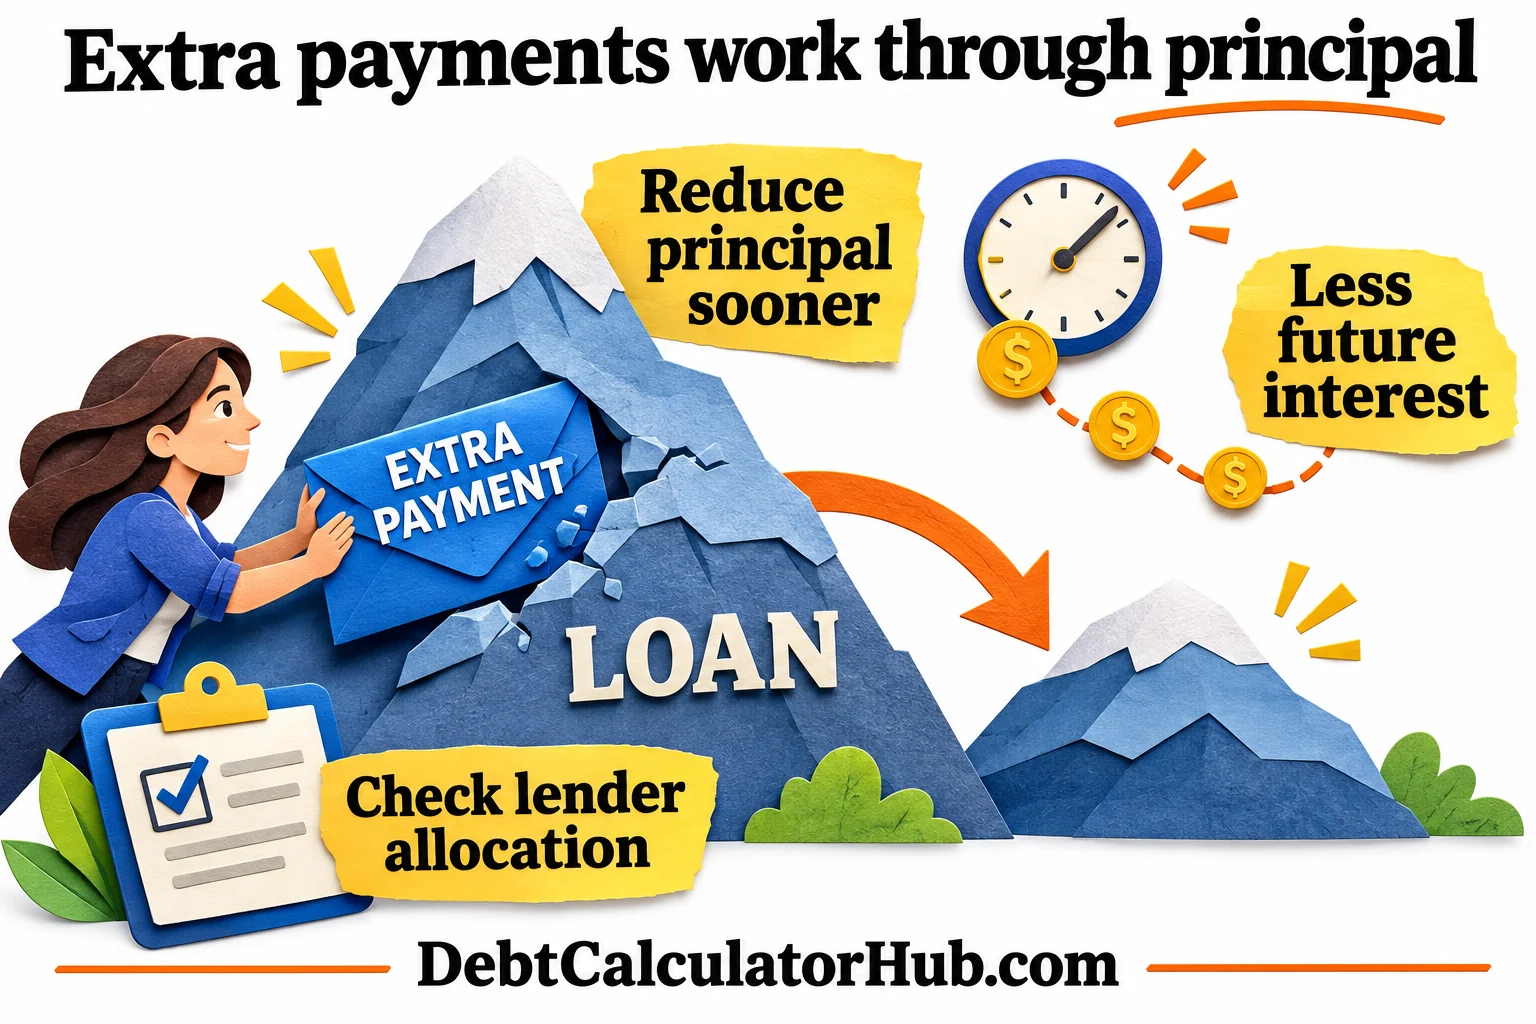
An extra payment calculator shows what changes when you pay more than the required monthly amount. The key idea is simple: interest is usually charged on the balance that remains. When an extra payment reduces principal earlier, the next month starts with a smaller balance, so less interest can accrue. That effect can repeat every month, which is why a small consistent extra payment may save more than people expect.
This is especially useful for credit cards, personal loans, car loans, and other debts where interest makes slow payoff plans expensive. Paying only the minimum can keep a balance around for years because part of each payment is absorbed by interest. Adding even $25, $50, or $100 per month can move more money toward principal and shorten the timeline.
To use this calculator, enter your current balance, annual interest rate, and current monthly payment. Then enter an extra monthly amount or tap one of the preset buttons. The calculator compares two payoff paths: your current payment with no extra amount, and the same payment plus the extra amount. The highlighted savings show the estimated months saved and interest saved, while the chart compares the two timelines side by side.
Finding extra money does not always require a dramatic budget change. Some people use canceled subscriptions, negotiated bills, overtime, tax refunds, cash-back rewards, small freelance income, or rounded-up payments. A practical approach is to send the extra amount soon after payday so it does not disappear into everyday spending.
Before relying on the estimate, check how your lender handles additional payments. Ideally, extra money should be applied to principal, not held for future scheduled payments. Also remember that actual results can vary if rates change, fees are added, or payments post on different dates. Use the estimate as a planning guide, then confirm details with your lender or servicer.
Reproduce a $50-extra payment example
Enter a $5,000 balance, 18% annual interest, a $150 current monthly payment, and $50 extra. This monthly model compares $150 with $200 paid each month: estimated payoff falls from 47 to 32 months, with about $669.64 less interest. The final payment may be smaller than the regular payment.
The baseline keeps your current payment fixed. It does not model a credit card issuer’s minimum payment shrinking as your balance falls. The extra amount repeats monthly; it is not a one-time lump sum. Rates stay constant, interest is added monthly before payment, and the estimate excludes new borrowing, fees and prepayment charges.
Read the full worked comparison and assumptions. For month-specific extra amounts, use the free six-debt planning workbook.
Sources and calculation notes
Our numerical examples use the monthly model described in our methodology. For account rules and terminology, see:
Content updated November 3, 2026. Examples are illustrations, not lender offers or account-specific payoff quotes.