
How it works
How a target payoff date changes the plan
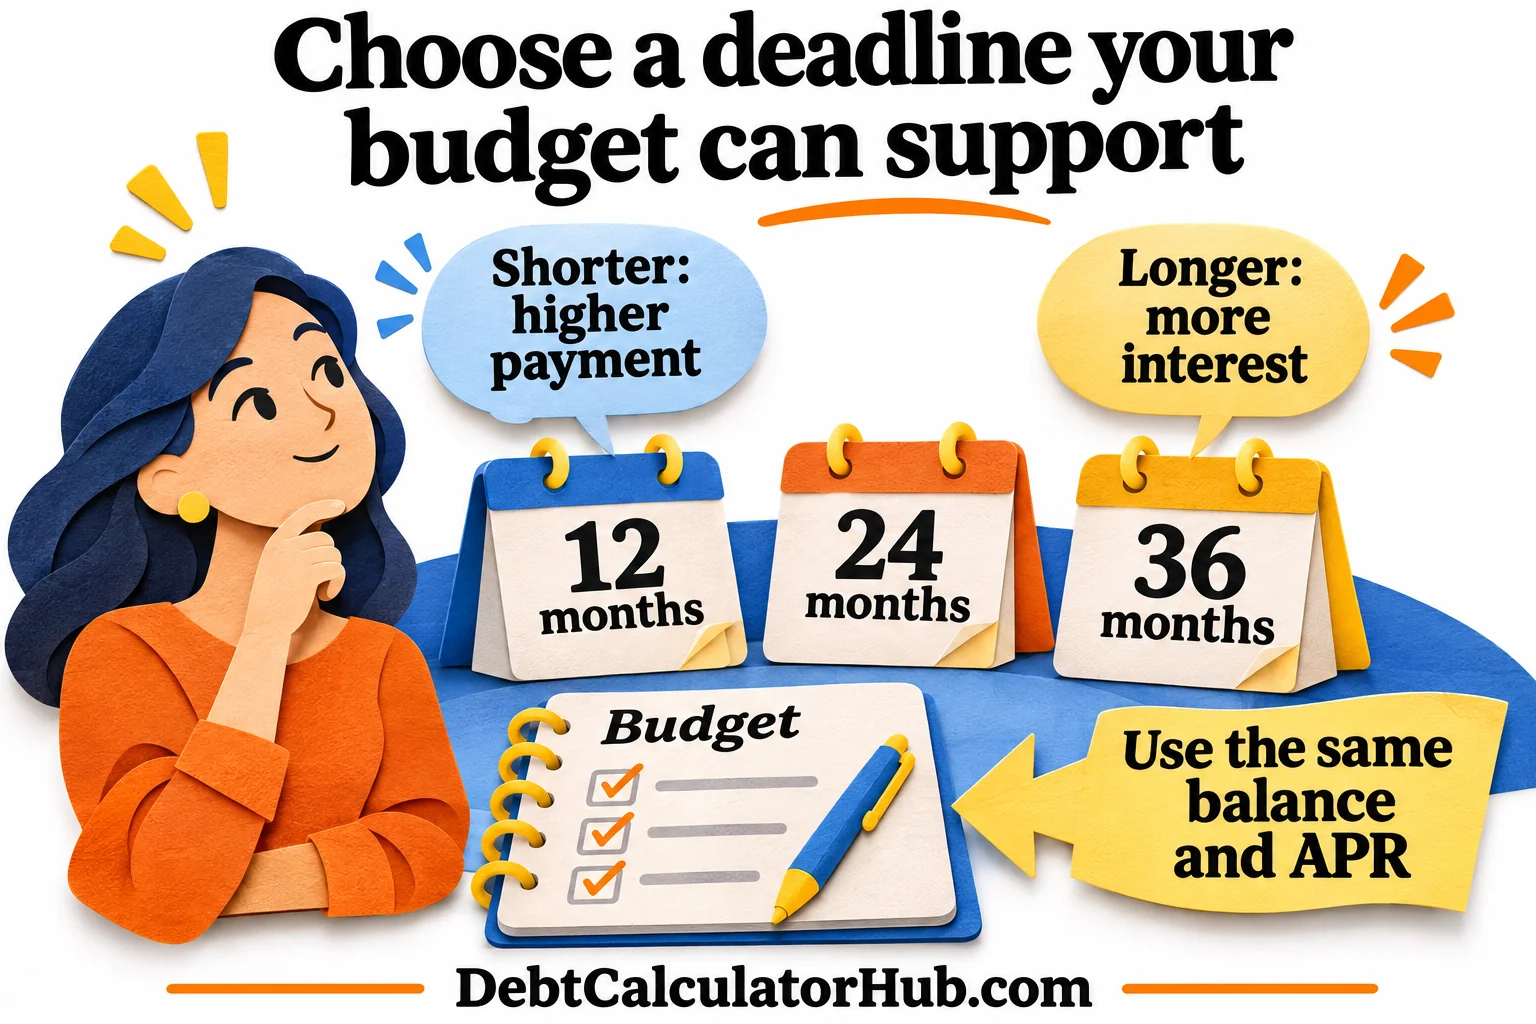
A target payoff plan starts with the deadline instead of the payment. If you want a credit card gone in 12, 24, or 36 months, the key question is how much you would need to pay each month to make that happen. This calculator estimates that payment using your balance, APR, and selected timeframe.
The shorter the target, the higher the required monthly payment. The tradeoff is that a faster payoff usually reduces total interest because the balance stays lower for fewer months. For high-APR cards, even a few months can make a noticeable difference.
This page is useful when you are building a budget around a specific goal. You may want a card paid off before a move, before applying for a loan, or before a promotional period ends. The calculator gives a monthly payment estimate and a month-by-month balance table so you can see whether the goal looks realistic.
If the required payment is too high, try a longer timeframe, look for ways to reduce the APR, or combine this result with a balance transfer or debt consolidation estimate. The numbers are educational estimates and do not replace your card issuer's payoff quote.
How the required payment is calculated
For balance B, monthly rate r = APR ÷ 100 ÷ 12, and n monthly payments, the formula is B × r ÷ (1 − (1 + r)−n). At 0% APR it becomes B ÷ n. The payment is rounded up to cents, then used in the monthly simulation; the final payment is limited to what remains.
For example, $6,000 at 24% APR over 24 months requires $317.23 monthly in this model. The modeled interest is about $1,613.42. A 12-month target raises the payment to $567.36 but lowers interest to about $808.29.
Use a future month or a positive whole-month timeframe. The estimate assumes the first payment occurs one month from now, with no new charges or rate changes. A target is useful for budgeting, but your issuer's statement controls the actual minimum due and due date.
Sources and calculation notes
Our numerical examples use the monthly model described in our methodology. For account rules and terminology, see:
Content updated September 21, 2026. Examples are illustrations, not lender offers or account-specific payoff quotes.