
By Debt Calculator Hub · Updated November 4, 2026 · Methods and editorial standards
Start with the target date
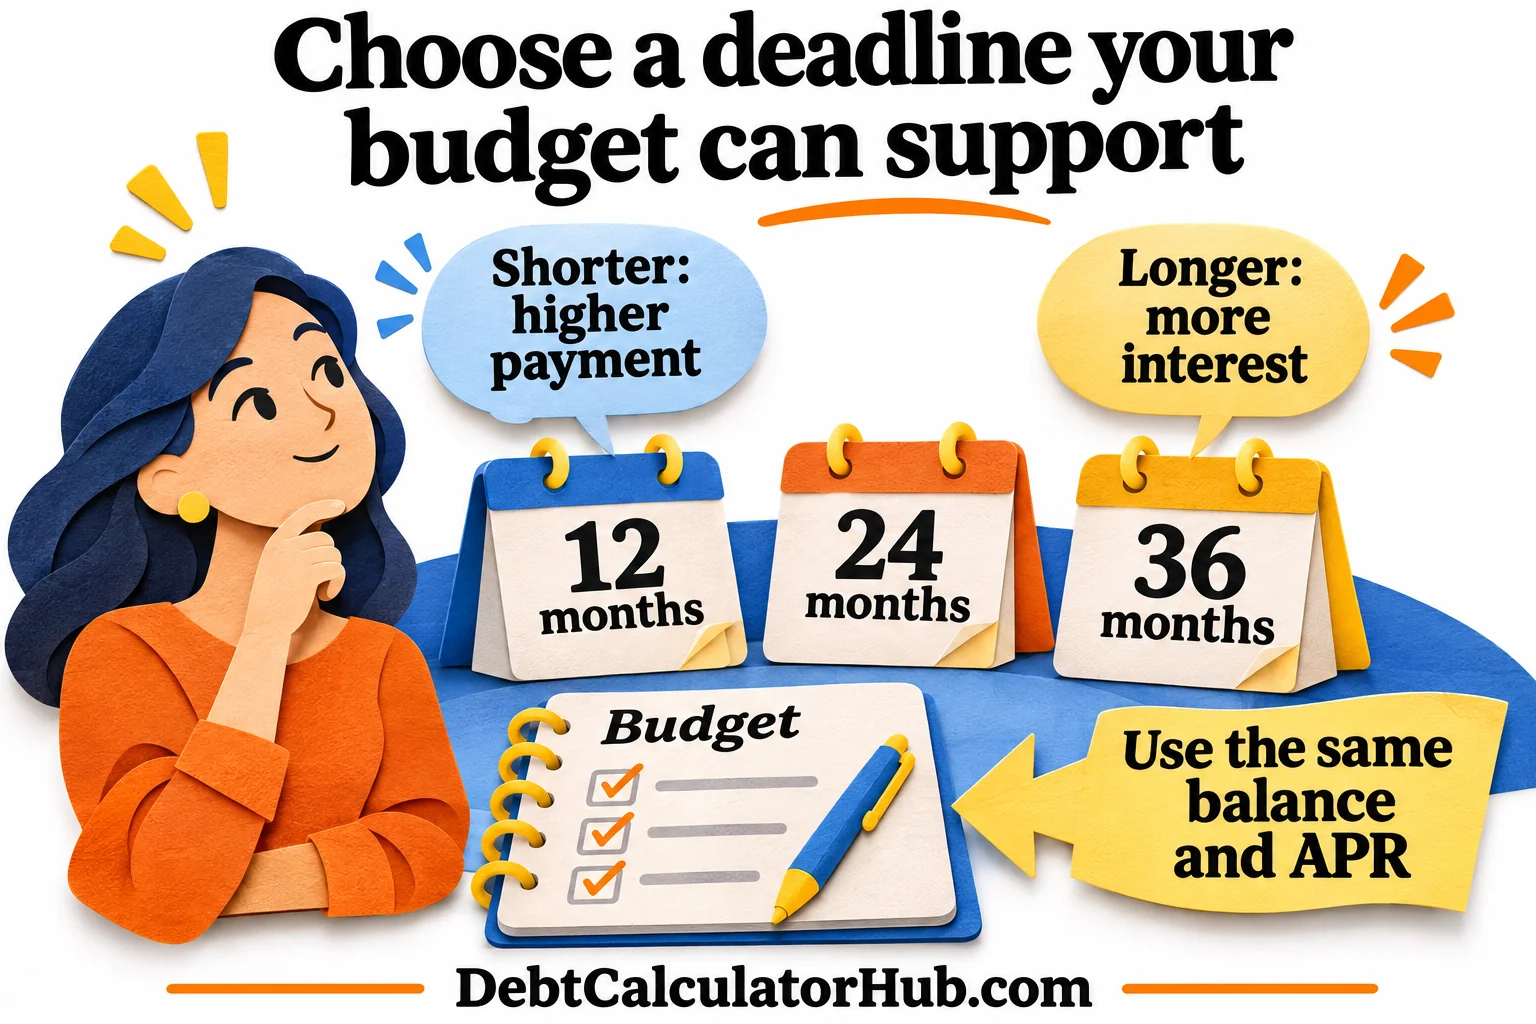
A target payoff plan begins with the finish line. Instead of asking how long your current payment will take, you choose a timeline first: 12 months, 24 months, or 36 months. Then you calculate the payment required to reach that goal. This approach is useful because it turns a vague goal like “pay this card off faster” into a specific monthly number.
The right timeline is not always the shortest one. A payoff plan has to fit your income, other bills, savings needs, and the risk of unexpected expenses. The best target is aggressive enough to create progress but realistic enough to repeat.
12 months: fastest, but hardest
A 12-month payoff can save the most interest because the balance has less time to accrue finance charges. It can be a good goal for a smaller balance, a temporary income boost, or a card you want cleared before applying for another loan.
The challenge is cash flow. A one-year payoff may require a monthly payment far above the minimum. If that payment forces you to use the card again for groceries, gas, or emergencies, the plan may not work. Before choosing 12 months, make sure the payment still leaves room for essentials and a small buffer.
24 months: compare the budget tradeoff
A 24-month payoff requires less per month than a 12-month plan at the same balance and rate, but accrues more interest. It still creates urgency, but the required monthly payment may be easier to fit into a normal budget. For many people, two years is short enough to stay motivated and long enough to avoid breaking the rest of the budget.
Interest still matters over 24 months, especially on high-APR cards. If the payment looks close to what you can afford, check whether lowering the APR could help. A balance transfer, promotional rate, or negotiated hardship plan can change the result, but only if the fees and terms are reasonable.
36 months: slower but structured
A 36-month payoff is slower, but it can still be much stronger than drifting with minimum payments. It may make sense if you have several debts, inconsistent income, or a need to rebuild savings at the same time.
The main downside is total interest. A longer timeline gives interest more months to accumulate. If you choose 36 months, consider making extra payments whenever income allows. You can treat the 36-month payment as the baseline and use bonuses, tax refunds, or side income to accelerate the plan.
How to choose your target
Start with the payment you can repeat. Then test the timeline. If a 12-month plan creates stress, compare 18 or 24 months. If 24 months still feels too high, compare 30 or 36 months. The goal is to find the fastest plan that does not create new debt.
You should also consider the card’s APR. A high-APR card rewards speed because every month saved reduces expensive interest. A lower-APR card may allow a slightly longer timeline while you focus on higher-cost debt first.
What to do if the required payment is too high
If the calculator shows a payment you cannot afford, do not ignore the result. Use it as information. You can extend the timeline, lower expenses, increase income, sell unused items, or search for a lower APR option. You can also combine methods: pay a steady amount each month, then add occasional extra payments when possible.
Avoid building a plan around money you are not sure you will have. A smaller payment that happens every month usually beats an ambitious plan that collapses after two billing cycles.
Use the calculator
Enter your balance, APR, and target months. The calculator estimates the monthly payment needed and the total interest for that timeline. Test several timelines side by side. When one payment feels realistic, use it as your starting plan and revisit it whenever your income or expenses change.
A $6,000 balance: three concrete timelines
At a constant 24% APR, the monthly rate in this model is 2%. The required payment is rounded up to the next cent so paying the displayed amount reaches the target. The last payment can be smaller.
| Target | Monthly payment | Total interest |
|---|---|---|
| 12 months | $567.36 | $808.29 |
| 24 months | $317.23 | $1,613.42 |
| 36 months | $235.40 | $2,474.25 |
The 12-month option needs $250.13 more each month than the 24-month option but avoids about $805.13 in interest. That saving is useful only if the higher payment fits your budget without forcing new borrowing. Start with the largest sustainable payment, rather than a deadline that leaves no room for essentials.
These estimates assume a steady rate, monthly interest added before payment, no new borrowing, and no late fees. Payments continue until the final smaller payment clears the balance. Actual statements can differ because of daily accrual and posting dates. The estimate also assumes the APR stays constant. If a promotional rate expires before your target date, the remaining balance may accrue interest at a different rate; check the offer terms and test a conservative rate for the months after the promotion ends.
Use the related calculator
Turn this guide into a concrete estimate with the calculator built for this topic.
Calculate Your Required Monthly Payment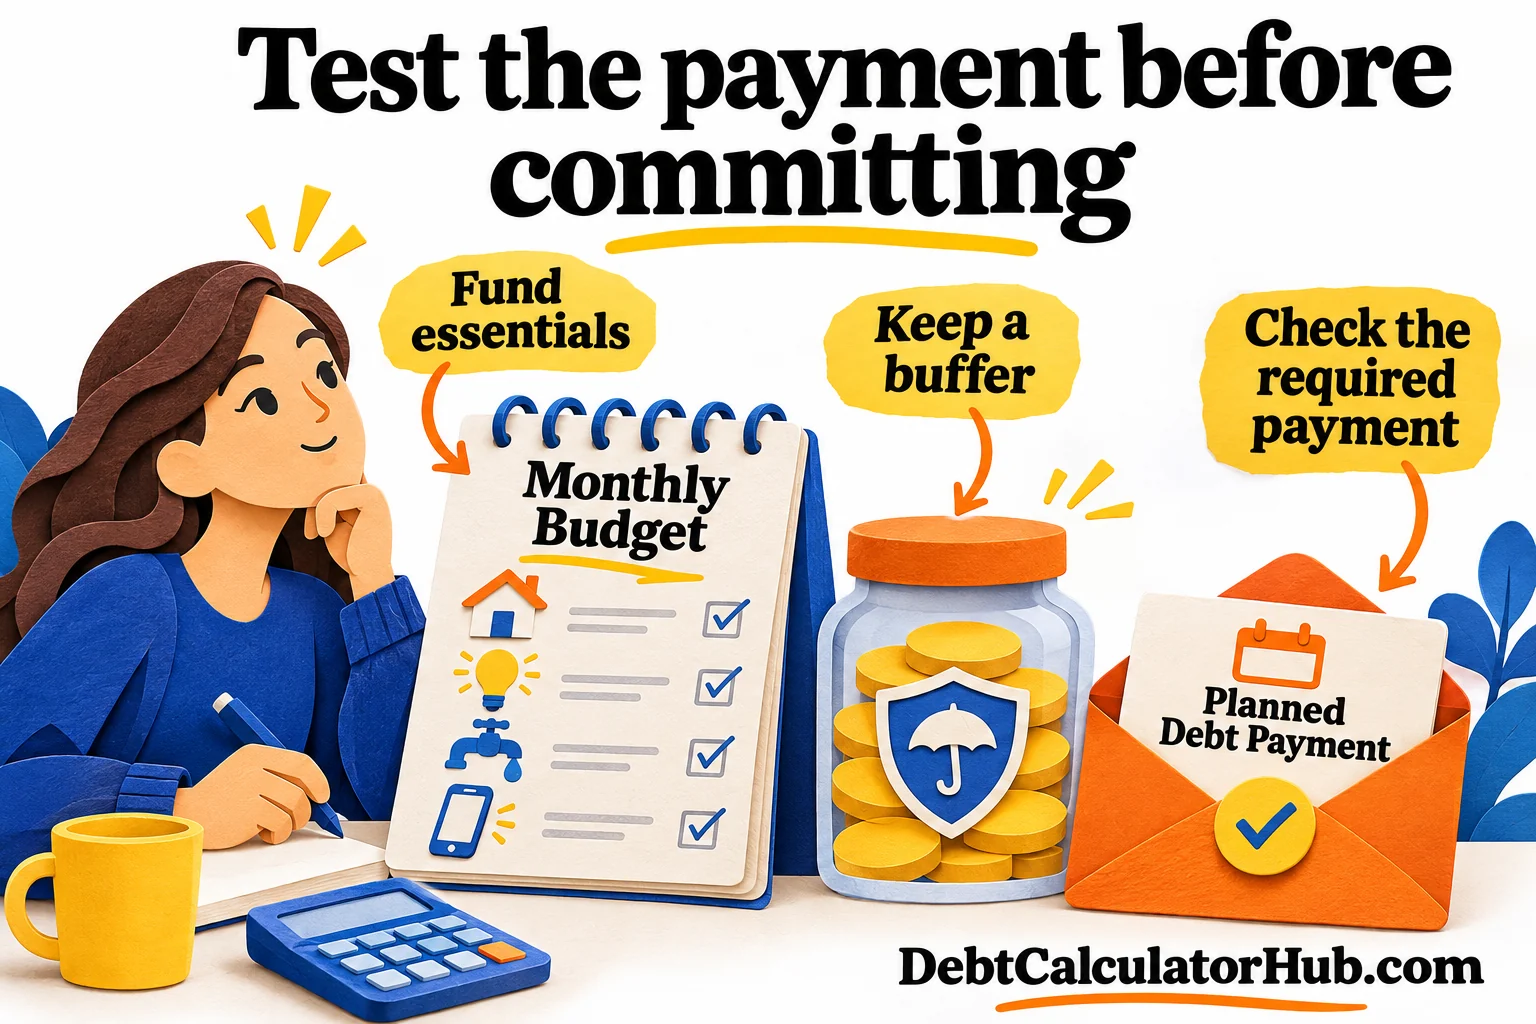
Test the payment against a repeatable budget
The $6,000 at 24% example requires $317.23 for 24 months or $235.40 for 36 months in this model. If $250 is reliably available after essentials and other required payments, the 36-month target fits that amount; the 24-month target has a $67.23 monthly shortfall. An uncertain future bonus should not silently fill that gap.
Choose a target using income you can repeat, then test a lower-income month before scheduling payment. Recalculate when the APR, balance or available payment changes. A calendar date is approximate because the model counts monthly payments, not actual statement dates. Check the issuer’s minimum each cycle: a target payment must still meet the contractual requirement even if your original estimate was lower.
Download the free complete debt payoff planner
Choose a repeatable budget, then change extra payments month by month as needed. The complete workbook supports six debts, a 120-month schedule, a selectable Snowball or Avalanche priority, month-specific extra payments, and an actual-payment log.
Download the complete free planner and guide (ZIP)
Get the workbook only (XLSX) · Prefer one debt? Get the free starter
No payment, email signup or account connection is required to download. The workbook calculates one selected strategy at a time, uses fixed starting minimums with monthly interest, and excludes new borrowing, fees, rate changes and missed minimums. It is a planning estimate, not a lender payoff quote. The ZIP includes setup instructions, a hypothetical example and a personal-use license.
Sources and calculation notes
Our examples use the simplified monthly estimates described in our methodology. For the real-world terms and details discussed in this guide, consult these primary sources:
- CFPB: a card statement’s estimated three-year payoff payment
- CFPB: interest calculations that can make estimates differ from a card statement
Reviewed October 22, 2026. Examples are illustrations, not lender offers or account-specific payoff quotes. Actual terms and results depend on your account and lender.