
By Debt Calculator Hub · Updated November 4, 2026 · Methods and editorial standards
Watch the minimum shrink over time
Use the formula shown in your card agreement. Both plans start with the same balance and APR; only the payment rule changes.
The percentage is applied to the balance before that month’s interest. The floor applies until the last smaller payment clears the debt. The fixed payment must cover the first modeled minimum. Estimates stop at 600 months. Values stay on this page; they are not saved or sent. Read the model assumptions.
Why minimum payments feel harmless
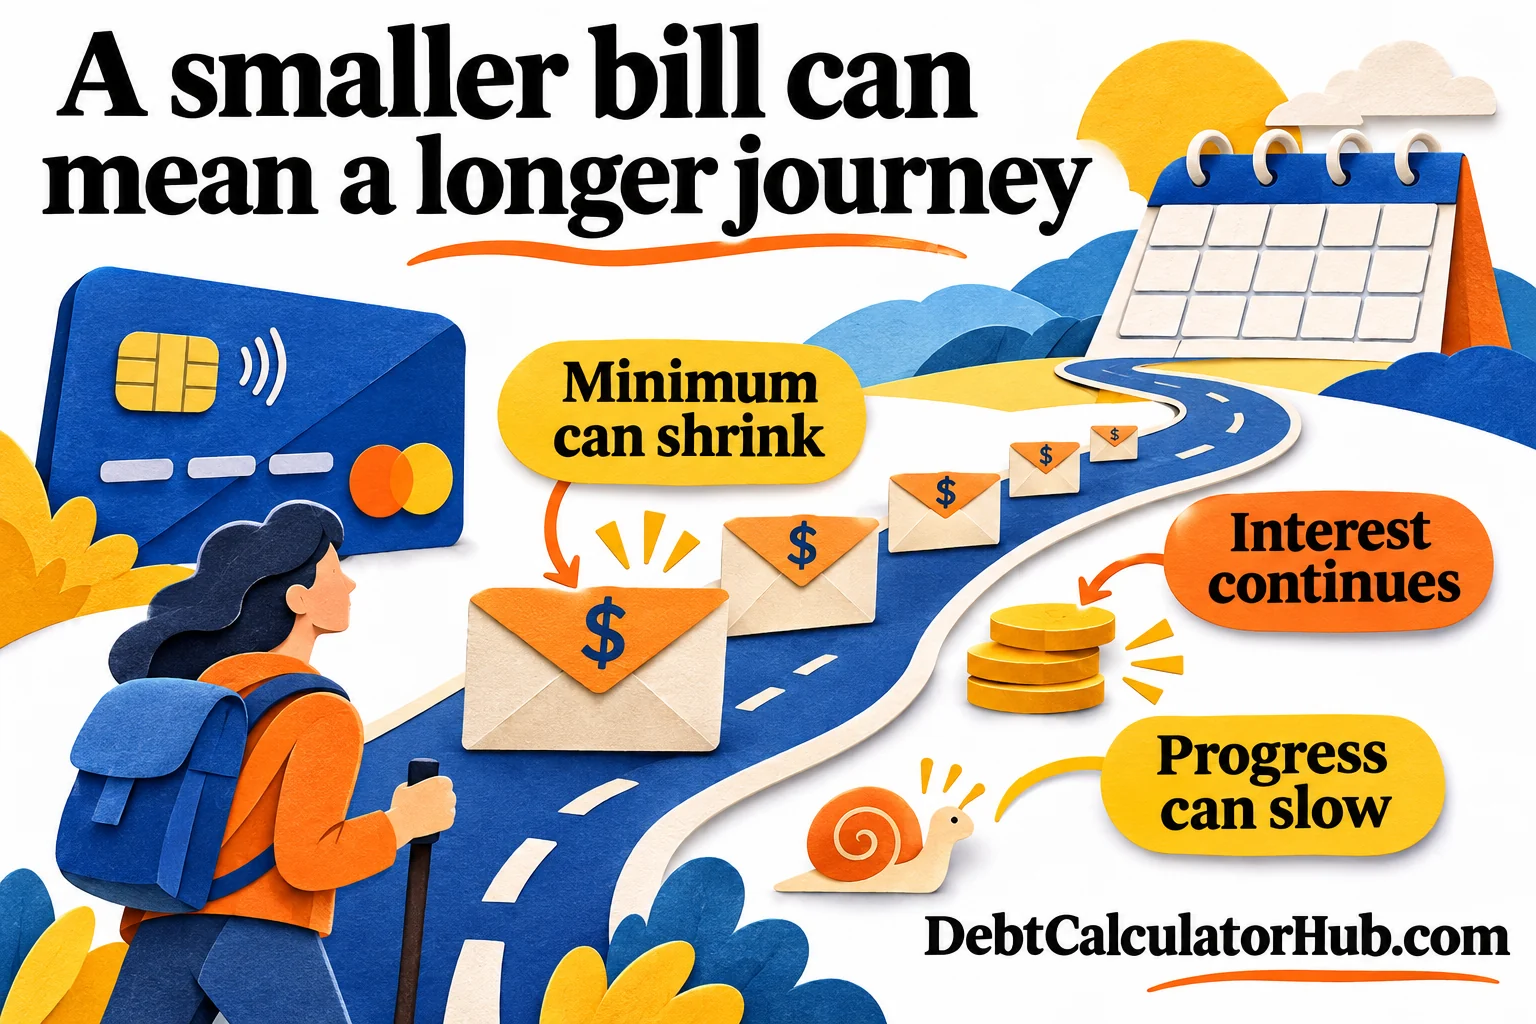
A minimum payment looks small because it is designed to keep the account current, not to erase the balance quickly. That difference matters. When a credit card statement says the minimum due is affordable, it can create the feeling that the debt is under control. In reality, the account may still be expensive if the annual percentage rate is high and the payment mostly covers interest.
For many cardholders, the danger is not one dramatic mistake. It is the quiet habit of paying the minimum month after month while the balance barely moves. The account stays open, the required payment looks manageable, and the true payoff date stays far away.
What makes minimum payments expensive
Three numbers drive the cost: the balance, the APR, and the minimum payment formula. A common estimate is a small percentage of the balance, a fixed dollar floor, or the greater of several values. If the balance is large and the APR is high, the minimum payment may reduce principal slowly.
This is why two people with the same balance can have very different payoff timelines. One person may pay the minimum and stay in debt for years. Another may pay a fixed amount above the minimum and cut the timeline sharply. The APR is important, but the payment amount is the lever most people can control immediately.
A simple example
Consider a $5,000 card at 18% APR. With a minimum defined as 2% of opening balance or $25, whichever is greater, the first payment is $100 and the first modeled interest charge is $75. Only $25 reduces the principal. The worked comparison below follows that declining payment rule.
Now compare that with a fixed payment that is two or three times the initial minimum. The monthly commitment is harder, but the balance falls faster. More of each future payment goes toward principal instead of interest. The result is usually fewer months and less total interest.
Why the payment shrinking is a problem
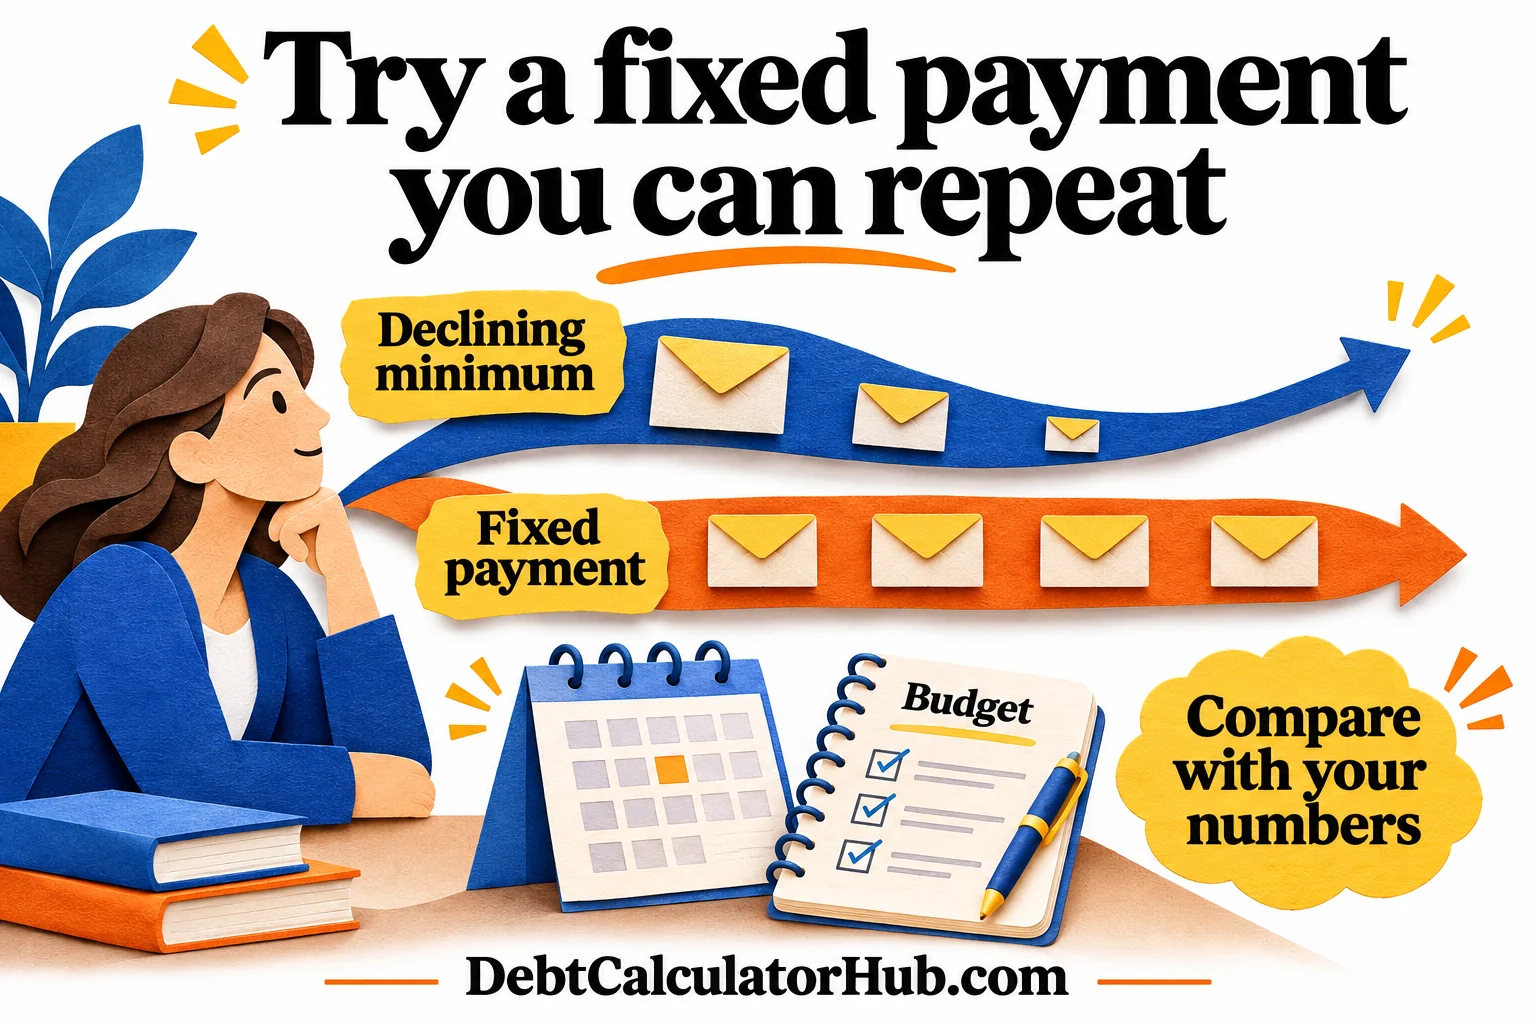
A declining minimum can ease the immediate monthly bill, but it also reduces the amount directed to principal. Keeping an affordable payment fixed as the minimum falls can shorten repayment. If a percentage-only minimum does not cover interest, there is no payoff under those assumptions.
A fixed payoff amount avoids that problem. If you can afford $200 per month today, keeping that payment steady as the balance falls creates a faster payoff path. The payment does not have to be huge; it just needs to be meaningfully above the minimum and repeatable.
How to use this information
Start by checking your statement for the APR and minimum payment rule. Then estimate the minimum-only payoff path. Do not stop at the monthly payment amount. Look at the number of months and the total interest. Those two numbers show the real cost of convenience.
Next, test a few alternatives: paying twice the minimum, paying three times the minimum, or choosing a fixed amount that fits your budget. The goal is not to shame yourself for paying the minimum during a hard month. The goal is to understand what happens if the minimum becomes the long-term plan.
Ways to improve the result
The fastest improvement is usually to stop adding new charges and pay more than the minimum. If the APR is very high, you can also explore a lower-rate option, such as a balance transfer or a hardship arrangement. Those options only help if the fee and terms make sense and if you avoid building a new balance.
Small extra payments can still matter. An extra $25 or $50 may not feel dramatic, but it reduces principal earlier. Earlier principal reduction means future interest is calculated on a smaller balance.
Bottom line
Minimum payments can be useful in an emergency, but they are usually a slow and expensive payoff strategy. If you can pay more, even modestly more, the long-term difference can be meaningful. Use the calculator to compare the minimum-only path with a larger payment before deciding what your monthly plan should be.
Recalculating the minimum changes the answer
Take $5,000 at 18% APR. Define the minimum as the larger of $25 or 2% of the opening monthly balance, rounded up to cents. The first minimum is $100; first-month interest is $75, leaving $4,975 after payment. The next minimum is $99.50.
| Payment rule | Payoff time | Interest |
|---|---|---|
| Declining 2%, $25 floor | 370 months | $12,323.57 |
| Fixed $100 every month | 94 months | $4,311.18 |
The fixed-payment path is not a minimum-only path once the contractual minimum declines. A different formula, 1% of opening principal plus monthly interest with a $25 floor, starts at $125 and takes 222 months with about $6,537.45 interest in this model. Check the statement instead of assuming either example matches your issuer.
These estimates assume a steady rate, monthly interest added before payment, no new borrowing, and no late fees. Payments continue until the final smaller payment clears the balance. Actual statements can differ because of daily accrual and posting dates.
Use the related calculator
Turn this guide into a concrete estimate with the calculator built for this topic.
Open the Minimum Payment CalculatorSources and calculation notes
Our examples use the simplified monthly estimates described in our methodology. For the real-world terms and details discussed in this guide, consult these primary sources:
- CFPB: the three-year repayment estimate on a credit card statement
- CFPB: how credit card interest is calculated
Reviewed October 22, 2026. Examples are illustrations, not lender offers or account-specific payoff quotes. Actual terms and results depend on your account and lender.